NEVADA

Life Insurance, Supplemental Protection & Annuities in Nevada

Insurance for the life
you’re building—
and the
future ahead.

Explore life insurance, supplemental protection and insurance-based retirement options through the questions that matter to Nevada individuals, families and business owners.

Product-specific guidance requires confirmed licensing, appointments and availability.

A LIFE, CONNECTED.NV / D·BG
Nevada, with connected protection topicsAn abstract Nevada outline connects life, health events, care, business, retirement and legacy. Points represent educational topics, not office locations or product availability.LIFEHEALTH EVENTSCAREBUSINESSRETIREMENTLEGACYNVPEOPLE FIRST. POLICIES SECOND.
Abstract illustration. Points represent life questions, not offices or confirmed service areas.
LIFE INSURANCE • SUPPLEMENTAL PROTECTION • ANNUITIESA PERSONAL STARTING POINT

A CONNECTION BEYOND THE POLICY

For Mendy Douglas,
Nevada is home.

Douglas Benefits Group was founded by Mendy Douglas. Nevada is her home and resident state, giving this page a personal connection to the place where she lives. That connection is a starting point for conversation, not a substitute for understanding a contract.

The goal is straightforward: make room for questions, explain the differences and help people understand the commitment behind a policy. No street address or local office is implied.

Nevada remains planned in the licensing configuration. Residence does not establish an active license or available products.

Meet Mendy

THE QUESTION BEFORE THE PRODUCT

Start with the responsibility.
Then look at the insurance.

People rarely start with a policy name. They start with a person, a responsibility or a question about what could change. The insurance conversation should begin in the same place.

Insurance products are tools for different problems. A death benefit, a payment for a qualifying hospital event, a benefit associated with care at home and a retirement income option are not interchangeable.

Before a product comes into view, consider who depends on you, what would change and what resources are already available. Douglas Benefits Group’s approach is to explain relevant insurance categories and their limits so the purpose remains clear.

  • If something happens to me, what happens to my family?
  • How would my household replace my income?
  • What happens to my business?
  • What would an unexpected hospital stay do to our finances?
  • What if I need qualifying care at home?
  • How do I create income later in retirement?
  • What do I want to leave behind?

CHOOSE THE RESPONSIBILITY

What are you
protecting?

Choose a starting point to reveal educational topics and a question worth asking. There may be more than one concern on your mind.

TOPICS YOU MAY WANT TO EXPLORE

Put names to the responsibilities.

A partner, children or other dependents may need different kinds of financial support after a death. Think about the transition they would face, ongoing expenses and the resources they could already use.

These topics are educational, not individualized product recommendations. A selection does not determine eligibility, suitability or state availability.

01 / LIFE INSURANCE

Life Insurance in Nevada

The policy isn’t the point.
The people and responsibilities
behind it are.

A life insurance decision involves a purpose, an amount, a duration and a commitment. Each deserves attention before comparing policy names.

Income replacement may be the first concern, but it is rarely the only one. Mortgage or rent, debts, children, other dependents, education goals and final expenses can all form part of the picture. The value of caregiving and other unpaid contributions can matter alongside a paycheck.

A business obligation may require separate attention from family support. A legacy goal may continue after working years end. Longer-term family protection can involve a different time horizon from a loan that will eventually be repaid.

The appropriate type, amount, term and policy design vary considerably. Begin with the financial need, account for existing coverage and assets intended for that purpose, and consider what premium commitment fits your circumstances. Avoid treating a rule of thumb as an individual answer.

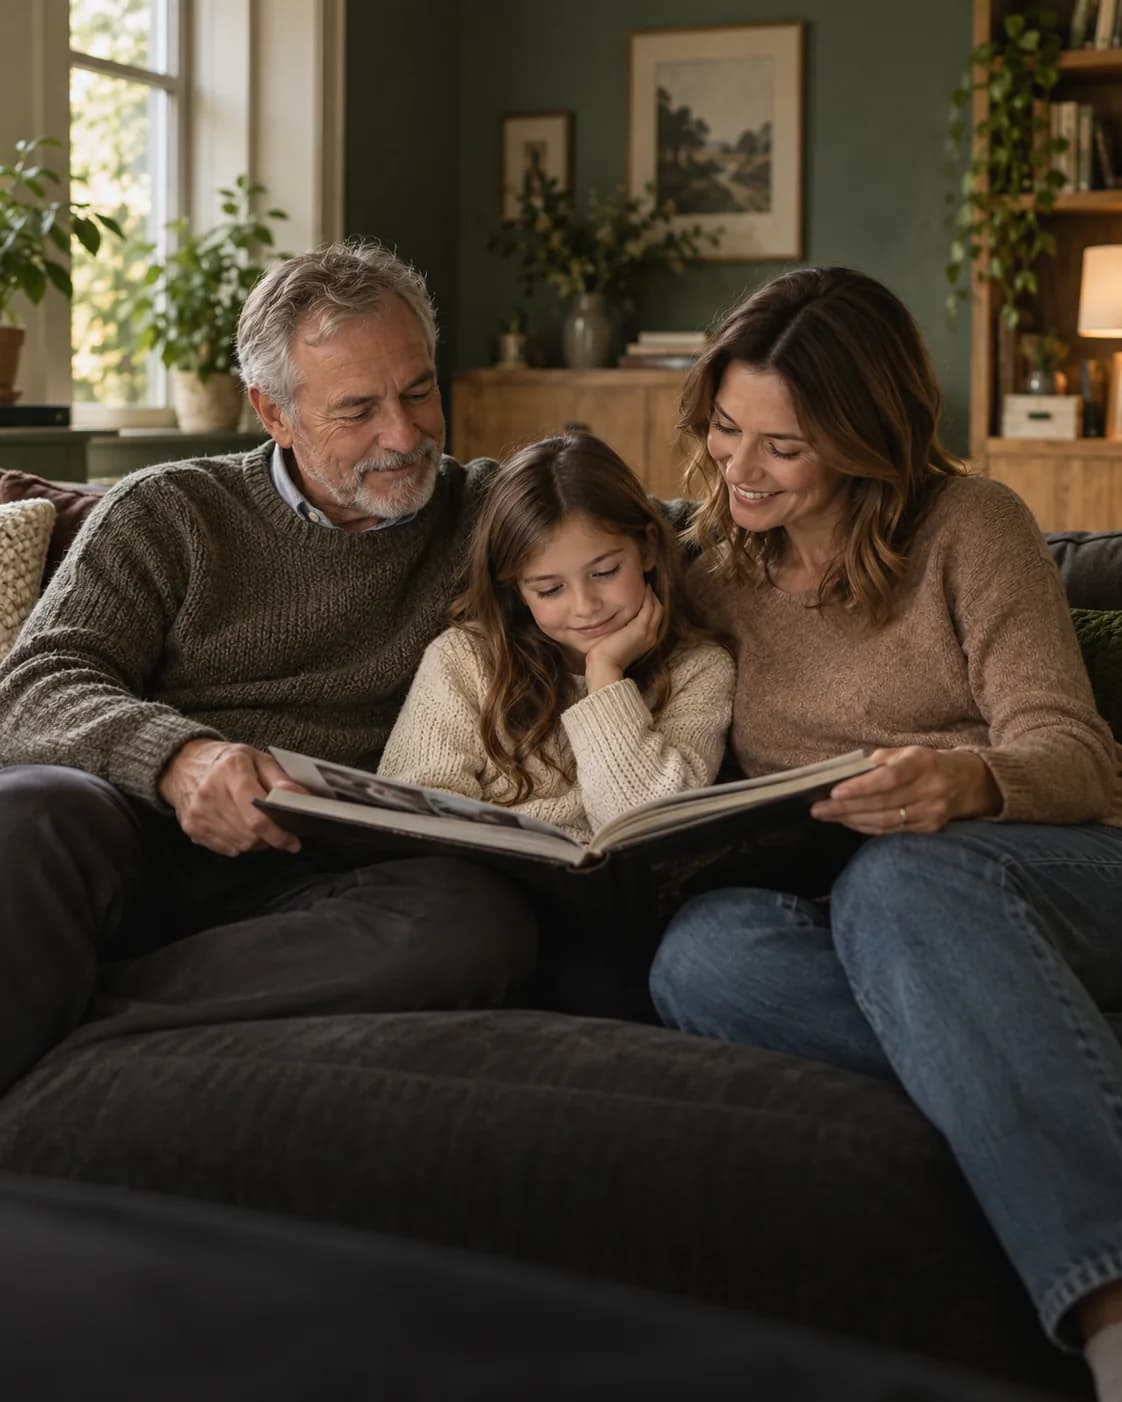
Family members from three generations sharing a photo album at home
A person.
A purpose.
A longer view.

The calculator organizes potential needs. It does not calculate premiums, select a policy or establish underwriting eligibility.

01

The amount

What gap would remain after existing policies and resources are considered?

02

The duration

Which responsibilities are temporary, and which might continue for life?

03

The commitment

What payment and policy-management requirements could you maintain?

PROTECTION FOR A DEFINED PERIOD

Term Life Insurance in Nevada

A time-specific obligation
deserves a time-specific question.

Term life generally provides a death benefit during a specified period, according to policy terms.

Someone may explore term insurance for income replacement during working years, raising children, a mortgage, debt or a temporary business obligation. The intended coverage period should be compared with how long that responsibility could remain.

Traditional term life generally does not build cash value. Its central purpose is protection for a covered death while the policy remains in force. It should not be evaluated as though it has the same features as cash-value coverage.

Review the premium schedule and what happens when the initial term ends. Some contracts offer renewal or conversion rights, subject to deadlines and other provisions. Those features and any later premium changes must be confirmed in the policy.

Initial premiums are generally lower than for a comparable permanent death benefit, but no premium or eligibility can be established from that comparison alone. Insurer underwriting and the selected product determine an actual offer.

Explore Term Life Insurance

WHEN THE RESPONSIBILITY MAY CONTINUE

Permanent Life Insurance in Nevada

Permanent coverage is designed around longer-term protection, provided its funding and other policy requirements are satisfied.

The category includes different designs. Depending on the product, features may include cash value, contractual guarantees and different premium structures. Traditional whole life generally has scheduled premiums and guaranteed cash values; universal life designs have their own funding and crediting mechanics.

Some policies permit access to available cash value through loans or withdrawals. Access is subject to contract terms. Loans generally accrue interest, and loans or withdrawals can reduce values and death benefits, contribute to lapse or create tax consequences in some circumstances.

A permanent death-benefit need may involve long-term support, final expenses or a legacy. The premium commitment and consequences of early surrender deserve as much attention as the potential benefits. Not all premiums become accessible cash value, and cash value is generally not added to the stated death benefit at death.

Permanent insurance is not universally better than term. Guarantees depend on the issuing insurer’s claims-paying ability and the policy’s terms. Compare the actual purpose, cost and obligations rather than the category name alone.

Explore Permanent Life Insurance

LOOK AT ONE DIFFERENCE AT A TIME

Different jobs.
Different kinds of life insurance.

Purpose

Term life

Protection centered on a covered death during a specified period.

Permanent life

Protection intended for an enduring death-benefit need when policy requirements continue to be met.

What financial job should the death benefit do?

This comparison does not choose a policy for you. Needs, duration, affordability and the actual contract determine the discussion.

For additional independent education, the NAIC life insurance consumer guide explains policy categories and questions to ask before buying.

PERMANENT LIFE / UNDERSTAND THE DETAILS

Indexed Universal Life Insurance in Nevada

Indexed Universal Life, or IUL, is permanent life insurance. Its death benefit, cash value and funding requirements belong in the same conversation.

A portion of interest crediting may reference an external market index under a formula set by the contract. The policyholder is not directly investing policy cash value in that index. A change in an index is not the same as the amount credited to a policy.

Caps can limit credits. Participation rates identify the portion of an index change used in the calculation. Floors and spreads may apply. Review which provisions can change and which minimums, if any, are guaranteed.

Policy charges and cost of insurance reduce values. Premium flexibility exists within policy requirements; it does not remove the need for adequate funding. Review how charges and funding interact over time, especially if contributions are reduced or paused.

FOUR PARTS OF ONE CONTRACT

01

Death benefit

Protection subject to an in-force policy and its provisions.

02

Cash value

Values affected by crediting, funding, costs and access.

03

Index-linked crediting

A formula, not direct ownership of a market index.

04

Contractual flexibility

Permitted changes with consequences to understand.

A 0% index-crediting floor
does not mean policy values
can never decline.

Where a floor applies, it relates to the crediting calculation. Policy charges, loans, withdrawals and other factors can still reduce overall value. Insufficient funding can result in lapse.

Policy loans usually accrue interest. Loans and withdrawals may reduce cash value and the death benefit. Lapse or surrender with an outstanding loan may create tax consequences; tax treatment depends on individual circumstances and applicable law. Consult an appropriate tax professional.

IUL requires ongoing review. Compare guaranteed provisions with non-guaranteed illustrations, monitor actual values and revisit funding as circumstances change. No accumulation result or retirement income outcome is promised.

NEVADA ENTREPRENEURS & BUSINESS OWNERS

When you own the business,
your financial life can
get complicated fast.

ONE OWNER / CONNECTED RESPONSIBILITIES

The household

Family income
Personal guarantees
Future retirement

The company

Debt & ownership
Partners & employees
Business income

A conversation map, not a legal or ownership structure.

For an entrepreneur, family income and company finances can depend on the same person. A protection conversation should distinguish those responsibilities without overlooking their connections.

A successful company may hold value in equipment, receivables, real estate or ownership interests. That value may not be readily available when a household needs income or a business needs to meet an obligation. A possible future sale is not the same as cash on hand.

Consider the consequences of an owner’s death from both sides. Family members may need income support. The company may need funds to manage debt, maintain continuity or carry out an appropriately structured agreement between owners. Personal guarantees can connect the two.

Life insurance may sometimes play a role in broader business-owner protection planning. The intended purpose should guide a review of policy ownership, beneficiaries and the amount and duration of coverage. Agreements and legal obligations require qualified professional input.

Permanent life and IUL are products worth understanding if the objective involves lasting protection. Neither becomes appropriate simply because someone is an entrepreneur. Premium commitments, policy complexity and access restrictions should be considered alongside changing business cash flow.

Retirement introduces another question: how much future income depends on the continued success or eventual sale of the business? Keep that discussion separate from day-to-day operating funds and avoid assuming a policy solves every part of the owner’s financial life.

Explore IUL Considerations for Business Owners

Douglas Benefits Group does not provide investment, tax or legal advice. Coordinate company agreements, tax treatment and legal arrangements with appropriate professionals.

02 / WHERE WOULD CARE HAPPEN?

Different care.
Different coverage.

Where care takes place is only the beginning. The covered event, qualifying services and payment provisions determine what a supplemental policy may do.

TOPICS YOU MAY WANT TO EXPLORE

Begin with what happened.

Hospital indemnity education follows the event: a qualifying admission, confinement or other specified hospital circumstance. The contract defines payment; an actual bill does not by itself determine the benefit.

Does this event meet the policy’s definition?

Explore a category, not a personalized recommendation. A location or diagnosis alone does not establish a payable benefit.

SUPPLEMENTAL PROTECTION / HOSPITAL EVENTS

Hospital Indemnity Insurance in Nevada

The event is defined.
The benefit is defined.
Your questions should be specific.

Hospital indemnity insurance is supplemental coverage. Depending on the policy, qualifying covered hospital events may trigger predetermined benefits.

Potential benefit categories include admission, confinement, ICU-related events or other specified circumstances. The policy determines the definitions, benefit schedule, exclusions and limits. Do not assume that every hospital visit qualifies or that multiple benefits automatically apply together.

Health-plan cost sharing, transportation, childcare, household expenses and time away from work can coincide with a hospitalization. Money received may help manage those pressures. That does not mean the individual expenses themselves are insured or reimbursed by the policy.

Before comparing benefits, ask what documentation a claim requires, who receives payment and how the covered event is defined. An attractive benefit label is not a substitute for reading the schedule and conditions.

Hospital indemnity does not replace comprehensive major-medical health insurance. Douglas Benefits Group does not currently sell individual/family major-medical plans.

SUPPLEMENTAL PROTECTION / CARE AT HOME

Home Health Care Insurance Options in Nevada

Sometimes the care you want
is the care that lets you
stay home.

Certain insurance products may provide benefits associated with qualifying home-health-care needs according to their terms. Whether a particular service qualifies is a contract question, not something the product name alone can answer.

People may explore this category to prepare for future care, maintain independence or better understand the financial demands of support at home. Family caregiving can be part of that conversation without being assumed to replace professional help.

Preparation also means discussing practical arrangements. Who could help, what support might be needed and how it would be coordinated are separate from whether an insurance benefit is payable. Coverage cannot guarantee that a preferred provider or care setting will be available.

Ask about the services and providers covered, the requirements for a claim, payment methods and the limits on benefits. Waiting periods, benefit periods, amounts and medical eligibility must come from verified policy information. No single schedule applies to every product.

This category is not automatically Medicare, Medicaid, comprehensive major-medical insurance or long-term care insurance. Policies may address narrower needs, so compare the actual protection and gaps. Douglas Benefits Group does not currently market Medicare products.

Explore Home Health Care Coverage

03 / RETIREMENT & ANNUITIES

Annuities in Nevada

Older couple viewing artwork together in a quiet gallery
At some point, retirement planning
becomes an income question.

Retirement can change the job you want money to do. A contract built for accumulation may involve different decisions from one intended to provide a payment stream.

An annuity is an insurance contract. Depending on its design, it may address accumulation, future income, income longevity or certain principal-protection objectives. Start by defining the role it would play alongside other resources.

Contracts differ substantially. Interest-crediting methods, surrender periods, liquidity provisions, income choices and guarantees all affect the commitment. Compare these features together rather than focusing only on a single benefit.

Explore Annuities

Understand the exchange.

An income option can change access to money or the amount remaining for beneficiaries. Optional benefits may have costs and conditions. Ask what happens when income begins, when money is withdrawn early and when the owner or annuitant dies.

Keep funds for near-term needs in view before entering a long-term contract. Surrender charges and other provisions can reduce the amount received if plans change. Contract values, surrender values and income calculations are not automatically the same figure.

Guarantees depend on the issuing insurer’s financial strength and claims-paying ability and the contract terms. Tax treatment depends on individual circumstances and applicable law; consult an appropriate tax professional.

HOW INTEREST MAY BE CREDITED

Fixed Indexed Annuities

An external reference.
A contractual calculation.

A fixed indexed annuity may link part of its interest-crediting method to an external market index, under the contract’s rules.

The owner is not directly invested in the index. Caps, participation rates, spreads where applicable and floors can shape crediting. Ask which terms may change and how each strategy calculates interest rather than treating an index result as a contract result.

Review surrender periods, withdrawal allowances and liquidity restrictions. A crediting floor does not remove applicable fees, surrender charges or the effects of withdrawals. Contract guarantees must be understood alongside their conditions.

Income options may differ and may involve additional costs or restrictions. The choice can affect access to money and what remains for beneficiaries. No market return, high guaranteed return or unlimited liquidity is promised.

Guarantees are subject to the financial strength and claims-paying ability of the issuing insurance company and the terms of the contract.

Explore Fixed Indexed Annuity Concepts

EXPLORE THE CHANGE IN PURPOSE

Saving for retirement
and living on retirement income
are different challenges.

TOPICS YOU MAY WANT TO EXPLORE

How would the value develop?

An annuity’s value reflects its crediting method, applicable costs and money taken out. Read guaranteed provisions separately from non-guaranteed assumptions. A larger illustrated balance is not a promised result.

What determines the actual contract value?

These are concepts for further education, not a recommendation to buy or replace a contract. Actual features depend on the insurer, product, eligibility and state availability.

A HOME-STATE PERSPECTIVE

Across Nevada

Nevada is the founder’s home state. The licensing record remains planned, so Nevada is not currently represented as actively served.

Local connection and insurance authorization are different facts. Geographic service references will appear only after licensing is confirmed. No local office, address or city-specific product offer is implied.

Review Confirmed State Availability
FOUNDER PORTRAIT

Portrait forthcoming.

Mendy DouglasFounder | Douglas Benefits Group

MENDY DOUGLAS / FOUNDER

You should understand
what you’re buying.

And just as clearly, why you’re buying it and how it works.

Mendy brings approximately a decade of experience in life and health insurance, a degree in Advertising and a background in marketing, business and entrepreneurship. She is also a mother and grandmother, with a personal understanding of how responsibilities can change.

Nevada is home, but the approach is individual. A family, a business owner and someone preparing for retirement can arrive with very different concerns. The first conversation should make those concerns clearer before introducing product details.

An independent agent may consider options from more than one insurer where licensing, appointments and availability permit. That means explaining differences in purpose, guarantees, costs and limitations without suggesting every policy is right for every person.

  1. WHATThe purpose and the limits.
  2. WHYThe responsibility it may address.
  3. HOWThe terms and the commitment.
Meet Mendy

NEVADA / INSURANCE QUESTIONS

A clearer question.
A more useful answer.

Fifteen starting points for understanding life insurance, supplemental protection and annuities.

What types of insurance does Douglas Benefits Group offer in Nevada?

Nevada is Mendy Douglas’s home state, but the centralized record is not currently marked licensed. This page explains the planned focus on life insurance, supplemental protection and annuities, rather than an available offer. Individual/family major-medical plans are not offered, and Medicare products are not currently marketed.

What is term life insurance?

Term life is death-benefit coverage for a specified policy period. Payment requires a covered death while the policy is in force and satisfaction of its provisions. Review the initial term, premium schedule and any renewal or conversion terms before choosing a policy.

How are term and permanent life insurance different?

Term is organized around a defined period. Permanent life is intended for longer-term protection, may include cash value, and must be funded and maintained according to its terms. Duration, affordability and policy obligations should be compared together; neither category fits every need.

How much life insurance should I consider?

Consider the money needed for immediate obligations and ongoing support, then subtract existing coverage and resources intended for those purposes. Housing, dependents, education, debt and business responsibilities may affect the estimate. The calculator helps structure the questions without determining a suitable policy or guaranteeing eligibility.

Does term life insurance build cash value?

Generally, no. Traditional term premiums support protection during the policy term, rather than an accumulating cash-value feature. Check the specific contract for any unusual features instead of assuming a policy provides benefits associated with another category.

What is indexed universal life insurance?

IUL is permanent life insurance with death-benefit protection and cash value. Its interest-crediting formula may use an external index, subject to contractual limits. Charges, funding, borrowing and withdrawals also influence the policy, so ongoing review is important.

Is an IUL invested directly in the stock market?

No. The policy uses an index as a reference for calculating interest credits. The policyholder does not directly invest policy cash value in that index. Index performance alone does not describe the policy’s credited interest or net change in value.

Can IUL cash value decline?

Yes. Charges, cost of insurance, loans, withdrawals and other policy factors can reduce value. A 0% index-crediting floor, where applicable, limits that crediting calculation; it does not guarantee that the overall policy value cannot decline or that the policy cannot lapse.

Can Nevada business owners consider IUL?

An entrepreneur may explore IUL as one way to address a long-term life insurance purpose, alongside other options. Business cash flow, liquidity, ownership arrangements and the policy’s funding demands matter. It is not automatically appropriate for business owners. Availability requires confirmed licensing, appointments and insurer requirements.

What is hospital indemnity insurance?

Hospital indemnity is supplemental insurance with predetermined benefits for defined covered events. Depending on the policy, an admission, confinement or ICU-related event may qualify. Definitions, exclusions and limits determine payment, not a general description of having been hospitalized.

Does hospital indemnity insurance replace health insurance?

No. It does not replace comprehensive major-medical insurance. A scheduled benefit may help with expenses, but it need not equal medical bills or replace lost earnings. Keep its limited supplemental role separate from the role of medical coverage.

What is home health care insurance?

The name can describe products that provide specified benefits associated with qualifying care at home. Services, payment rules, duration and eligibility vary by contract. It should not automatically be treated as Medicare, Medicaid, major-medical coverage or comprehensive long-term care insurance.

What is an annuity?

An annuity is an insurance contract that may address accumulation or income objectives, depending on its terms. Compare how value is credited, access to funds and payment choices. Guarantees rely on the issuing insurer’s financial strength and claims-paying ability and the actual contract provisions.

What is a fixed indexed annuity?

A fixed indexed annuity may reference an external market index in its interest-crediting method. The owner is not directly invested in the index. Caps, participation rates, spreads and floors may affect crediting; surrender provisions, withdrawal rules and income choices also matter.

How do I get started with Douglas Benefits Group in Nevada?

Start with the educational pages and check the States page for confirmed licensing updates. A home-state connection does not establish authorization or product availability. Use the contact form to send a question. Submitting an inquiry does not provide a quote or start coverage.

KEEP EXPLORING

Understand it
before you buy it.

Browse All Resources

Supplemental Insurance / 8 MIN READ

What Is Hospital Indemnity Insurance and How Does It Work?

Hospital indemnity insurance is supplemental coverage designed to provide fixed benefits for certain covered hospital events. Learn how it works, what it doesn't replace and what to consider before choosing a policy.

THE NEXT STEP IS A CONVERSATION

Nevada is home.
Let’s make the
conversation personal.

Whether you’re protecting your family, preparing for unexpected care needs, building a business or thinking about retirement, start with a conversation about what you’re actually trying to accomplish.

BRING THE RESPONSIBILITY. BRING THE QUESTIONS.

Let’s start
with understanding.

Nevada licensing must be confirmed before product-specific assistance can begin.

Send your question through the contact form. Submitting an inquiry does not provide a quote, establish eligibility or start coverage. Product-specific assistance requires confirmed licensing and availability.

Contact Information & Availability

Your inquiry is sent through Formspree to Douglas Benefits Group. Topic choices express interest, not confirmed availability. Please do not include medical details, Social Security numbers, account information or other sensitive information. Read our privacy notice.

Your contact inquiry